

Green Dot - Mobile Banking

- 32.77K Reviews
- 3.5
- Downloads
- 5,000,000+
Our take on Green Dot - Mobile Banking from Appgk
I tend to judge a banking app by what happens on an ordinary day: checking whether a payment went through, confirming available money before buying groceries, or making sure a deposit has arrived. Green Dot - Mobile Banking is built for those routine moments rather than for people looking for a full financial planning suite. Developed by Green Dot, this free finance app gives phone-based access to Green Dot banking services, with a straightforward focus on managing money from a mobile device.
My overall impression is practical but measured. The app is useful when you already use Green Dot and want a convenient way to stay close to your account. It is less compelling if you expect the broad budgeting tools, investment features, or highly polished customer-service experience found in some larger banking alternatives. The important question is not whether it can replace every financial app, but whether it makes your existing Green Dot relationship easier to manage.
How Green Dot Mobile Banking feels today
The current release is version 4.69.5, and that matters because a banking app is never really finished. Small changes to account screens, sign-in behavior, alerts, or transaction handling can affect daily confidence even when the app’s basic purpose stays the same. I see this version as an established mobile companion rather than a brand-new experiment. It has been available since May 17, 2011, giving it a long history on Android.
That long presence also explains why the app feels focused. Green Dot is not trying to turn the phone into a complete financial command center. The experience is centered on seeing what is happening with your Green Dot money and taking care of common account tasks without visiting a branch or relying on a desktop browser. For an existing customer, that narrow purpose can be a strength: there is less to learn and fewer unrelated tools competing for attention.
Best Parts of Green Dot - Mobile Banking
Things to Keep in Mind About Green Dot - Mobile Banking
Green Dot - Mobile Banking has an average rating of 3.5 from around 91 thousand ratings, with roughly 33 thousand written reviews. I would not treat that score as a final verdict, because banking-app reviews often reflect account-specific problems, device issues, support experiences, and expectations about features that may not apply to everyone. Still, it is a useful reminder to approach the app as a functional tool with possible rough edges, not as a flawless replacement for every banking channel.
Its reach is substantial, with more than 5 million installs, and the app is rated for Everyone. It is free to install, which makes trying the mobile experience relatively easy for current Green Dot customers. The minimum Android requirement is version 7.0, so the compatibility range is broad enough for many older phones, although I would still keep the operating system and the app updated before relying on it for important account access.
News and Features Related to Green Dot - Mobile Banking

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
The everyday workflow I would use
Imagine getting paid or adding money to your account before a busy weekend. I would open the app first to check the available balance, then review recent activity rather than relying only on memory. After a few purchases, I would return to the transaction list and look for anything unfamiliar. This simple habit is more valuable than constantly opening the app without a reason: it turns the phone into a quick checkpoint for spending and account activity.
A useful detail in that routine is the difference between an account balance and money that is genuinely available for immediate use. Pending activity can make those figures feel confusing in any banking application. I would avoid making a purchase based only on a headline number and instead inspect recent transactions whenever timing matters. The app is most helpful when I use it as a confirmation tool, not as permission to spend every amount that appears on screen.
Don't want to read the full review?
I also recommend checking that notifications are configured in a way you can actually live with. Too many alerts become background noise, while too few can delay awareness of activity. The right setup depends on how often you use the account, but the principle is the same: alerts should support regular review, not replace it. If a notification looks unfamiliar, I would open the account directly and inspect the transaction rather than responding through a message.
Where the latest version fits in the product’s evolution
The move from a long-running banking service to a current 4.69.5 release suggests ongoing maintenance and product evolution, but I would be careful not to read more into the version number than it proves. A newer release can improve compatibility and smooth out existing workflows without transforming the app into something entirely different. In practical terms, existing users should expect continuity in the core experience, with refinements rather than a completely new way to manage money.
Screenshots
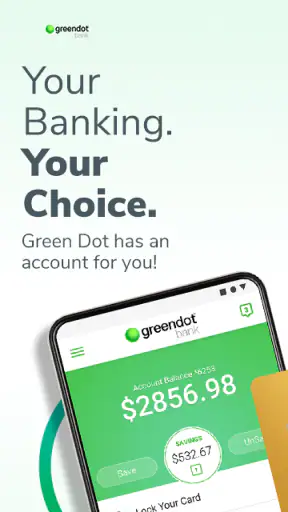
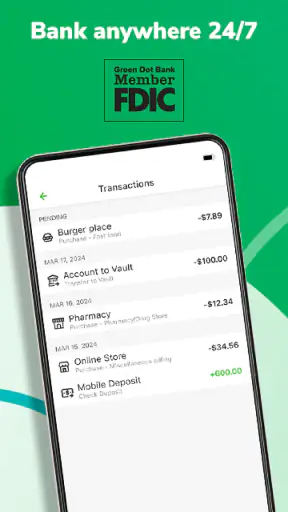
That is good news for someone who dislikes relearning financial tools. A familiar layout and established account flow can reduce mistakes, especially when you are checking a balance quickly or reviewing a purchase in a public place. The trade-off is that a conservative evolution may feel slow to users who want ambitious budgeting dashboards, detailed spending analysis, or richer financial planning in the same app.
For a person installing it for the first time, the current version should be judged as an access point to Green Dot services, not as a general-purpose money coach. I would install it with a specific task in mind: monitoring an existing account, reviewing activity, and handling normal mobile banking needs. That expectation makes the app easier to evaluate fairly and prevents disappointment caused by comparing it with products aimed at a different kind of customer.
What existing Green Dot users gain
The biggest benefit is convenience. If Green Dot is already part of your financial routine, having account access on a phone removes the need to wait until you can use a computer. That matters for small decisions: checking whether you can afford a purchase, confirming that money arrived, or reviewing activity after using the account during the day. These are not dramatic features, but they are the moments when mobile banking proves its value.
I also like the possibility of separating observation from action. You do not need to make a major account change every time you open the app. Regularly viewing activity can help you notice patterns, identify an unexpected charge, and understand how quickly your balance changes. For someone who normally avoids checking finances, a phone-based tool can make the habit less intimidating because the review takes place in short sessions.
There is a practical security advantage to staying informed, although no app can remove the need for careful account behavior. I would use a screen lock on the phone, avoid signing in on shared devices, and never treat an email or text asking for credentials as automatically trustworthy. The app can provide account visibility, but the user still controls many of the decisions that protect access.
Another benefit is consistency across ordinary situations. Whether I am at home, commuting, or standing at a checkout, the same mobile account can be the place I verify information. That consistency is especially useful for people who use Green Dot as a focused spending account rather than as the center of a complicated financial setup. The fewer places I need to check, the less likely I am to overlook a transaction.
Where it falls short compared with broader alternatives
Green Dot - Mobile Banking is not the right choice for everyone. If you want a detailed monthly budget, investment tracking, credit monitoring, or a unified view of several unrelated financial institutions, a dedicated finance platform may be a better fit. Those alternatives can be stronger at analysis because they are designed to compare categories, accounts, and long-term goals rather than simply provide access to one banking relationship.
A traditional bank app may also be preferable if you need a wide range of account products, extensive branch support, or a mature ecosystem that connects checking, savings, loans, and other services in one place. On the other hand, a general budgeting app may offer better visual reports while lacking the direct account-management role of Green Dot’s own application. The choice depends on whether your priority is controlling an account or understanding your entire financial life.
The app’s focused design can create friction when a problem is more complicated than a balance check. If a transaction needs investigation, an account-access issue appears, or you need a detailed explanation of a financial decision, a mobile screen may not be enough. I would not assume that every problem can be solved inside the app simply because the app is the fastest place to start. Sometimes the better workflow is to gather the transaction details in the app and then use the appropriate Green Dot support channel.
There is also a psychological limitation. A convenient balance screen can encourage reactive money management: checking whether there is enough for today without thinking about upcoming obligations. I would pair the app with a simple personal note, calendar reminder, or separate budget method if my finances were tight. Green Dot’s app can show account activity, but the discipline of planning still has to come from me.
Three habits that make the app more useful
First, I would review activity at deliberate points rather than opening the app randomly. A quick check after a cluster of purchases can reveal whether a payment is pending, duplicated, or simply larger than expected. This is more informative than looking only at the balance, because the transaction history explains why the number changed.
Second, I would use the app as a record for conversations with support. If something looks wrong, I would note the merchant description, amount, and date before contacting anyone. That preparation saves time and makes it easier to describe the problem accurately. It also prevents the common mistake of reporting a vague concern when the real issue is a delayed or unfamiliar-looking transaction.
Third, I would keep a backup access plan. A banking app is convenient, but a phone can be lost, damaged, offline, or unavailable. I would know how to reach Green Dot through another official route and keep essential account information handled securely. This is not a criticism unique to Green Dot; it is a sensible trade-off whenever a mobile application becomes the main doorway to money.
A fourth habit is to avoid judging financial health from one moment. I would compare the current activity with my own expected spending and upcoming commitments. That makes the app more useful for decisions such as whether to delay a nonessential purchase or move money through an approved method, rather than merely confirming that a transaction has appeared.
Who should install it and who should skip it
I would recommend it to existing Green Dot customers who want convenient account visibility on Android, prefer a focused banking tool, and are comfortable handling more complex questions through support when necessary. It is also a reasonable choice for someone who values a familiar mobile routine over a large collection of financial extras.
I would hesitate to recommend it as a first choice to someone seeking a complete personal-finance system. If your main goal is debt planning, investment management, household budgeting across several banks, or deep spending reports, you will probably need another app alongside it. Likewise, people who strongly prefer branch-based help or an all-in-one traditional banking relationship may feel that this focused experience does not cover enough ground.
The free price makes experimentation easy, but free access should not be confused with free financial services in every situation. Banking decisions can involve account terms and transaction conditions outside the app itself, so I would read the relevant Green Dot information before changing how I receive, spend, or move money. The application is a convenient interface, not a substitute for understanding the account behind it.
What I would watch in future updates
I would pay attention to whether future releases make transaction explanations clearer, reduce sign-in friction without weakening security, and improve the way the app helps users distinguish available money from activity still being processed. Those improvements would have a direct effect on everyday confidence because they address the moments when a banking app can create uncertainty.
I would also watch for better support handoffs. When a mobile banking issue cannot be solved on screen, the transition from the app to assistance should preserve useful context and make the next step obvious. That kind of improvement matters more to me than decorative redesign because it affects the stressful situations in which people need help most.
Finally, I would look for thoughtful expansion rather than feature overload. Green Dot could add value by making routine account monitoring clearer while keeping the main path simple. If new tools arrive, they should help users understand their money without turning a quick balance check into a maze of menus. The app’s strongest identity is its direct connection to Green Dot banking, and that focus is worth protecting.
After using it as a practical account companion, I see Green Dot - Mobile Banking as a sensible choice for the right customer, not a universal financial solution. Its long availability, current version, broad Android compatibility, and large installed base show that it has an established place in mobile banking. At the same time, the middling average rating and the focused scope tell me to keep expectations realistic.
My recommendation is simple: choose it when your priority is convenient Green Dot account access, and look elsewhere when you need a complete financial planning workspace. Used with regular transaction reviews, sensible phone security, and a backup support plan, it can make everyday money checks quicker and less awkward. I would install it for monitoring and routine control, while keeping another method available for detailed planning or complicated account problems.
Green Dot - Mobile Banking FAQ
What is Green Dot Mobile Banking, and who can use it?
Green Dot Mobile Banking is a financial app for managing eligible Green Dot accounts from an Android or iOS device. After signing in, users can generally review balances, monitor transactions, deposit checks when eligible, transfer money, and manage certain card settings. Availability depends on the specific Green Dot product, account status, identity verification, location, and the services supported by that account.
Is Green Dot Mobile Banking free to download and use?
The Green Dot app is typically free to download, but downloading the app does not mean every banking service is free. Depending on the account and transaction, users may encounter monthly fees, cash reload charges, out-of-network ATM fees, expedited transfer costs, or other service charges. Before using a feature, review the current fee schedule shown in the app and the terms for your particular account.
Can I deposit checks or add cash through the Green Dot app?
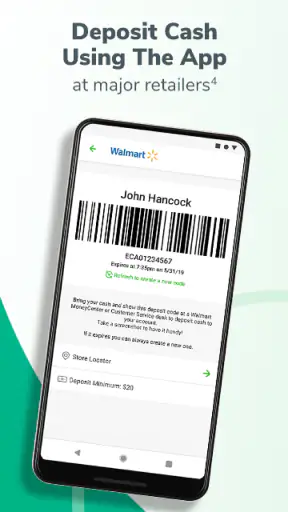
Eligible users may be able to deposit checks through the mobile check deposit feature by photographing the front and back of a properly endorsed check. Cash deposits may also be available through participating retail locations or supported deposit methods. Availability, limits, processing times, and fees can vary, so the app should be checked for the current instructions before relying on a deposit for urgent payments.
How secure is Green Dot Mobile Banking?
Green Dot Mobile Banking uses common security measures such as account credentials, device verification, encryption, alerts, and optional biometric sign-in on compatible devices. However, no banking app can eliminate every risk. Use a strong, unique password, avoid public Wi-Fi for sensitive activity, keep your phone and operating system updated, and contact Green Dot promptly if you notice an unfamiliar login, transaction, or lost device.
What should I do if I cannot sign in or my Green Dot card is lost?
If you cannot sign in, first confirm that your internet connection and app version are current, then use the official password or username recovery options rather than third-party websites. For a lost, stolen, or compromised card, lock or report it through the app if that option is available and contact Green Dot support immediately. Keep in mind that identity verification may be required before account access or card replacement.













